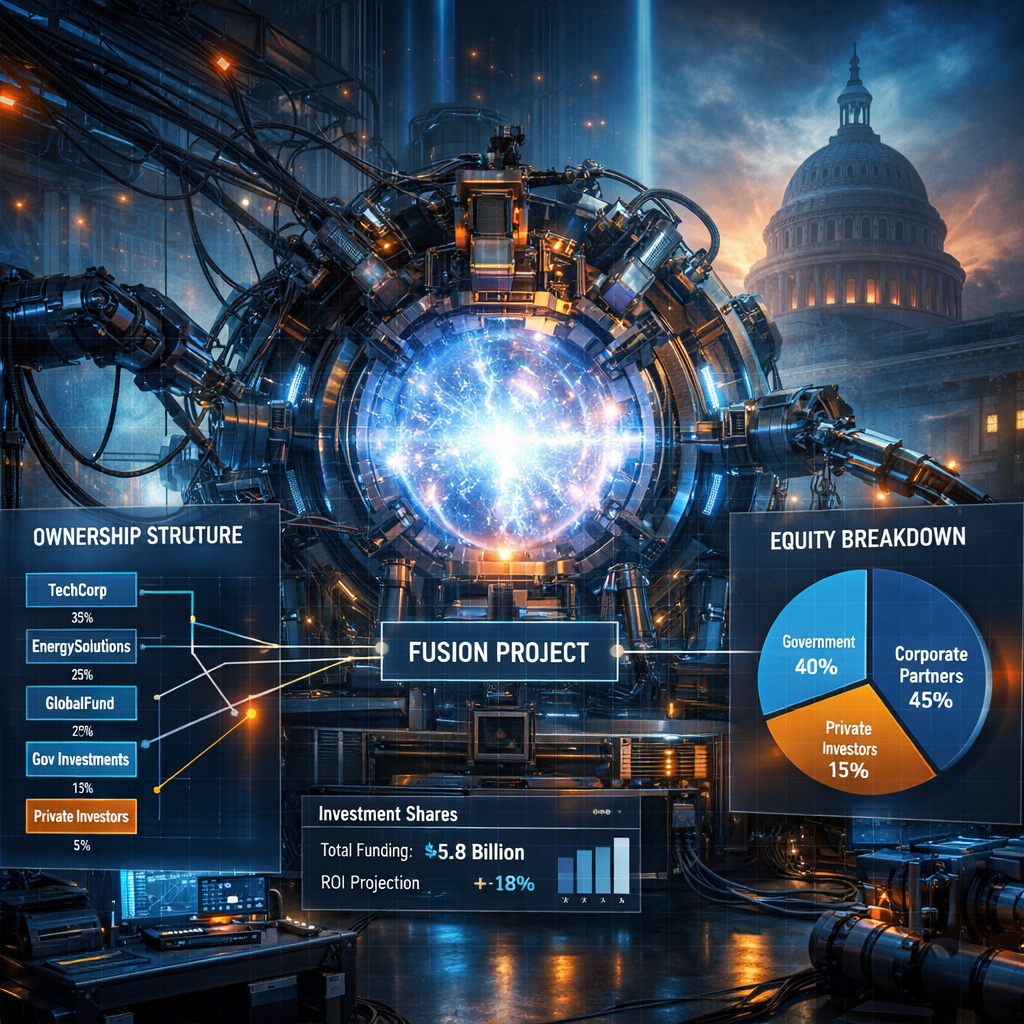
The U.S. government is making a new kind of play in the fusion energy space: instead of just writing checks, it’s asking for non-voting equity stakes in return. Under the CHIPS and Science Act, fusion startups Helion and Commonwealth Fusion Systems (CFS) have received government funding — $175 million and $85 million respectively — with each agreeing to give the U.S. government shares tied to their most recent valuations. For Helion, that stake is about 1 percent. The size of CFS’s share hasn’t been publicly disclosed. “Awards” like these are no longer purely non-dilutive funds.
What’s Changed for Fusion Funding
Historically, federal funding for fusion has come as grants where companies kept full control, no strings. That’s been especially true through programs like the Department of Energy’s Milestone Based Fusion Development initiative, which over its early years kept payments small. But as of last week, with these new awards bubbling up via the Department of Commerce rather than DOE’s research budgets, a new model is in motion.
CFS has raised roughly $4 billion in private investment to date; Helion about $3.2 billion. Quite large sums, but still dwarfed by what many analysts believe is needed for fusion to reach commercial scale. These new awards—though small relatively—are seen by industry as signals that the federal government is once again treating fusion as a strategic sector, ready to back commercial progress, not just basic research.
The Trade-Offs: Control, Upside & Investor Response
Government ownership may seem small, but it introduces notable trade-offs. Helion’s non-voting stake, estimated at ~1%, dilutes existing shareholders ever so slightly. It also means the government stands to gain if the company succeeds—but without having voting power. For other fusion firms, like CFS, Inertia Enterprises, Thea Energy, Avalanche Energy, and Pacific Fusion, this kind of arrangement has either not been required or opted out of. They keep their equity clean in exchange for non-equity contracts or lab partnerships.
Beyond dilution, there are questions about how these stakes affect future financing rounds, how liquidation or “pay-to-play” scenarios will unfold, and whether government shareholders will be treated differently if things go wrong. Some venture capitalists may see government equity as a hurdle: extra complexity in the cap table, extra conditions in investment agreements, or lowered appeal to private investors who dislike federal oversight or potential restrictions.
Precedents & Global Context
This model isn’t unique to fusion. Critical minerals firms like MP Materials and USA Rare Earth have given up significant equity—15 percent and 10 percent respectively—in exchange for large government awards and loans. Even Intel saw its equity altered under similar arrangements when the government converted promised funds into an ownership stake. Abroad, Germany’s Proxima Fusion has government entities on its cap table, backed by innovation agencies and climate tech funds.
These arrangements reflect growing global competition in fusion. Industry groups have called for substantial, one-time infusions of federal capital (in the billions) to push U.S. fusion infrastructure ahead. Meanwhile, countries like China are aggressively funding commercial fusion efforts. The U.S. is evidently trying to catch up, but with added terms.
The shift to equity demands marks a new chapter. For some startups, the trade-off may be acceptable: a chance to tap larger government sums, legitimacy, and strategic alignment. For others, especially those deeply reliant on private capital or sensitive to dilution and governance issues, the cost may outweigh the benefits.
It’s too early to tell whether this strategy will turbocharge the U.S. fusion industry or create fresh friction in fundraising, ownership, and control. What’s clear is that we are entering an era where government support isn’t just financial — it’s also a stake in the outcome. Startups, VCs, and policymakers will have to decide if the future they want is one defined by shared risks.